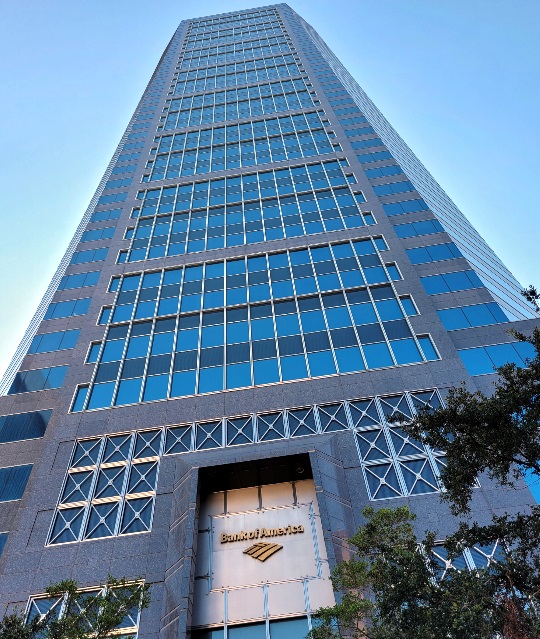
Bank of America office tower in Florida;
Photo by Thursday Review
Bank of America
Fined $1.2 Billion
For Failing to Intervene
In Illicit Finance
| published October 15, 2026 |
By Thursday Review staff
After a long, complex investigation by the U.S. Treasury Department and various law enforcement agencies, banking giant Bank of America has been fined $1.2 billion for ignoring security problems and failing to intervene in online banking scams, including money laundering and profits from patently illegal activities.
The fines against Bank of America are the third largest such punitive penalties ever levied against a U.S. bank for a systemic failure to regulate its clients and depositors. Bank of America has agreed to the outcome of the investigation and the fines, as has informed Wall Street that it must now lower expectations for its earnings for the third and fourth quarters.
Among the failures by BoA: according to the Treasury Department, the bank failed to report some $5 billion in “suspicious activity” to the appropriate federal and state law enforcement agencies, that the bank tolerated money-laundering, and that the bank ignored obvious signs of numerous illegal and illicit activity associated with its deposits and its banking transactions.
The bank also apparently side-kicked many of its problems directly to law enforcement, and sought to offload some of the issues by blaming other financial institutions as problems arose. And in other instances, BoA simply failed to provide adequate staff and training to its personnel to tackle specific reports of fraud or illicit activity even when customers called-in to report the issues.
BoA agreed to at least most of the findings, and offered apologies to Wall Street and to its customers. The bank’s disclosure of the fine was included on its Wednesday release of its third quarter earnings report.
“Financial crime compliance is serious,” BoA said in an announcement, “and we are responsible for getting it right. We have invested billions of dollars in technology and dedicated thousands of employees to combat financial crime, and our team is…committed to completing the work required to address the issues raised by our regulators.”
Under the agreement between BoA and the Treasury Department, Bank of America is required to hire an independent outside firm to review all past transactions and collect data on all suspicious activities and transactions going back as much as two years.
“When a bank of this size fails to meet its anti-omney-laundering and sanctions obligations,” Treasury Secretary Scott Bessent said, “the consequences extend far beyond its own walls, exposing the entire US financial system to significant illicit finance risks.”
The Bank of America consent order comes only about a week after American Express was fined $350 million by U.S. bank regulators for also failing to provide sufficient safeguards against money laundering and other illicit transactions through American Express and its subsidiaries.
The fines which have been assessed against Bank of America will surely impact its earnings for this year, though the company hopes to regain traction by the beginning of 2027. Over the summer, Bank of America has pledged a huge $250 billion lending program directed at U.S. infrastructure, including in technology, artificial intelligence, data centers, energy, and computer technologies.
Related Thursday Review articles:
U.S. Economy Added 162,000 New Jobs in August; By Thursday Review staff; September 4, 2026.
Bank of America to Inject $250 Billion Into U.S. Infrastructure; By Thursday Review staff writers; August 15, 2026.